Benafica is a health benefits and insurance company that helps employers offer flexible, tax-free health reimbursement plans instead of traditional group health insurance.

Contact Us
6701 Upper Afton Rd. Ste. 200, St. Paul, MN 55125

ICHRA · CHOICE Arrangements

ICHRA Administration for Any Size Employer

gradient divider

A successful ICHRA takes more than a platform.

Benafica brings the technology, administration, compliance, payment infrastructure, and people to make it work.

As of September 3, 2026: The Individual Coverage Health Reimbursement Arrangement (ICHRA) has a new name: CHOICE Arrangement. CHOICE stands for Custom Health Option and Individual Care Expense. 

For Employers

ICHRA with Benafica

An Individual Coverage Health Reimbursement Arrangement (ICHRA), also known as a CHOICE Arrangement, lets employers reimburse employees tax-free for qualifying individual health insurance and eligible medical expenses. Employers set the contribution, and employees choose their coverage.

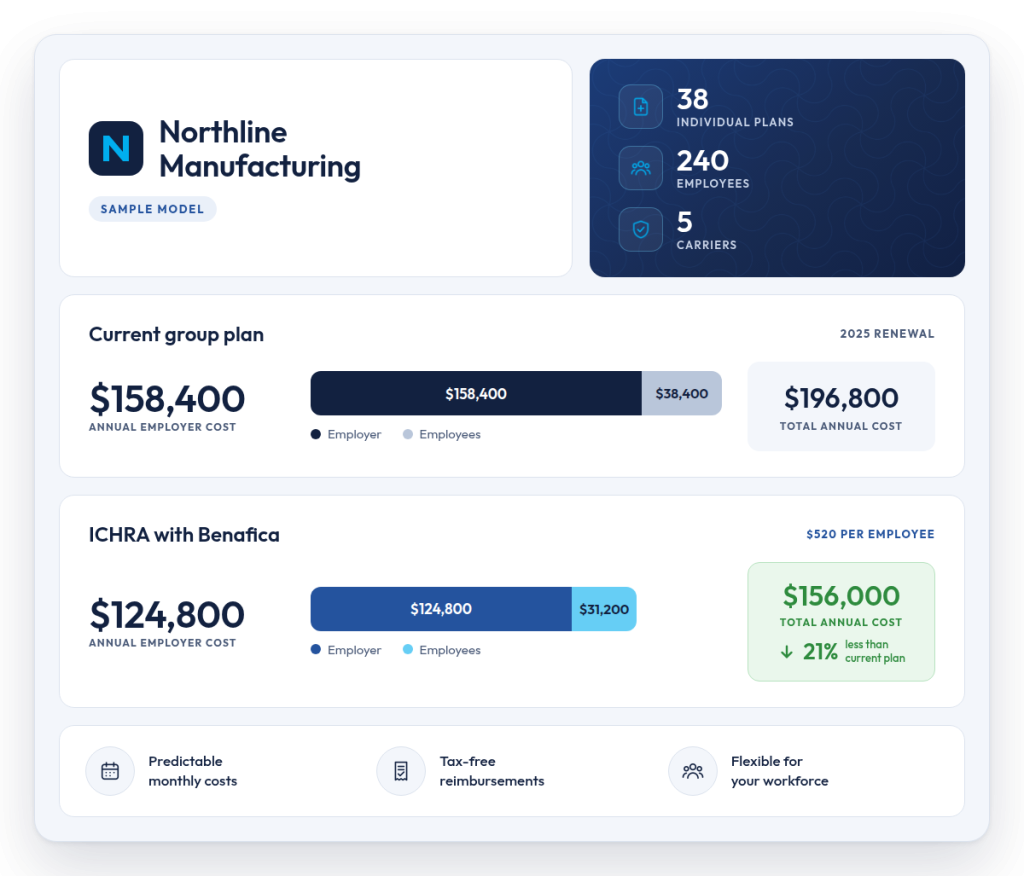
Northline sample model

Want a simpler benefit for a smaller team?

QSEHRA gives employers with fewer than 50 employees one monthly allowance for everyone, with no group plan to manage.

Benefits Made Simple

How ICHRA Works

Employer sets monthly allowance

Decide how much to contribute each month toward each employee’s healthcare costs, based on local individual market plans.

Employees choose coverage

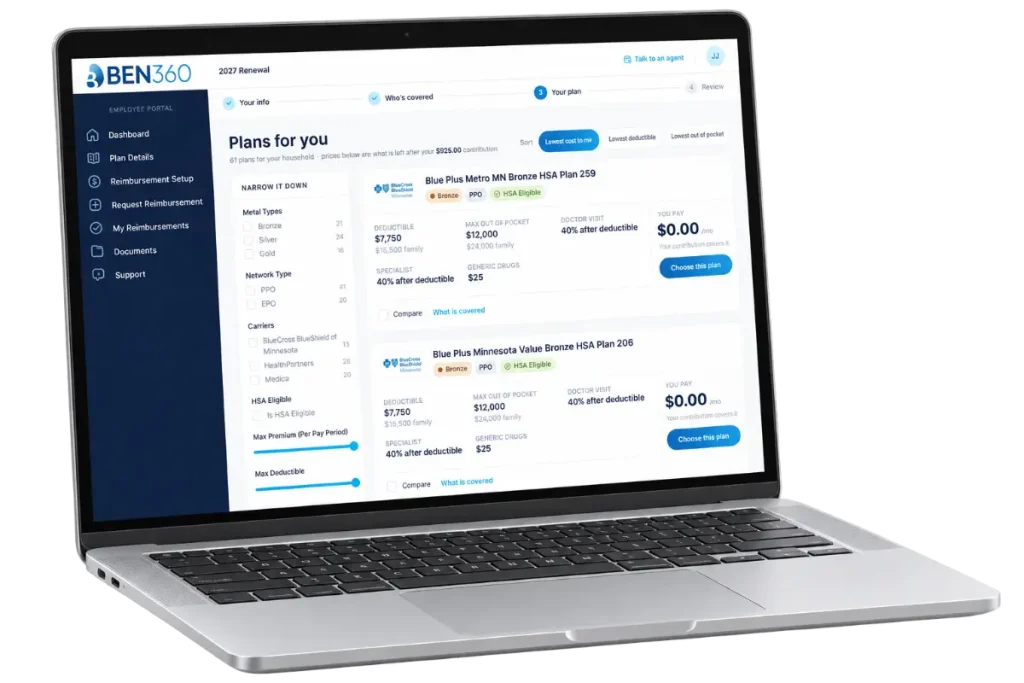
Employees shop, compare, and enroll in an individual plan that fits their needs — right inside the BEN360 platform.

We enroll and set up payments

We process enrollment behind the scenes and set up monthly premium payments so coverage stays active without extra work on your end.

Ongoing administration

New hires, terminations, and qualifying life events are all handled in one place, with support year-round.

End-to-end ICHRA support

We Handle the Administration

Running an ICHRA means handling plan documents, employee notices, coverage substantiation, premium payment and reconciliation, mid-year changes, payroll treatment, and year-end reporting.

Benafica Handles:

*Benafica provides administrative and reporting support but does not provide tax or legal advice. Employers remain responsible for reviewing, approving, and filing their required tax forms and should consult their tax advisor regarding their specific reporting obligations.

For Brokers

Expand Your Benefits Strategy

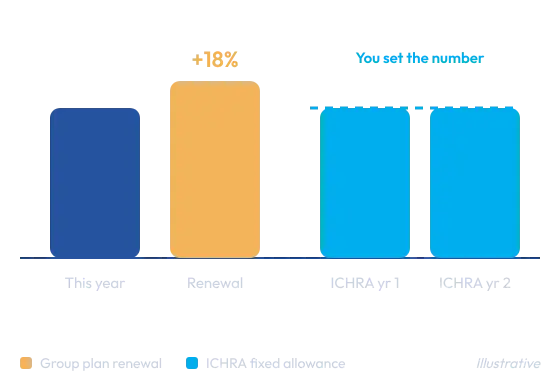
An ICHRA isn’t a product that replaces what you sell. It’s a second answer for the client whose renewal came back at eighteen percent. It also opens groups you couldn’t write before:

Benafica handles the administration. You keep the relationship.

Group renewals move. An ICHRA allowance doesn't.

Broker renewal chart
For Employees

More CHOICE in How You're Covered

Choose your plan
Shop for a plan that meets your needs, budget, doctors and prescriptions

Use your benefit
Your employer provides a monthly amount toward eligible coverage

Coverage through life changes
Change your coverage with qualifying life events, like marriage or having a baby

Take it with you
Your individual plan is yours. Keep it if you change jobs, so you're never starting over

SAMPLE COVERAGE · PER MONTH
employee 1 green background
100% covered

$567

Employer

$0

Employee

employee 2 blue background
83% covered

$695

Employer

$137

Employee

employee 3 orange background
75% covered

$846

Employer

$283

Employee

employee 4 yellow background
67% covered

$640

Employer

$315

Employee

ICHRA platform

Meet BEN360: Our ICHRA Platform

Available in all 50 States

ICHRA is a federal arrangement, so employers can offer it wherever their team lives and works.

FAQ

ICHRA Frequently Asked Questions

Employers of any size can offer an ICHRA. You need to have at least one W-2 employee. An ICHRA typically starts to make more sense for employers with 5 or more employees.

Most employers start by looking at current benefits spend and local individual-market premiums for their employees’ ages and locations. From there, they choose an allowance strategy. With a flat-dollar strategy, you offer a flat amount to all your employees (or employees across a group). With an age-banded strategy, you offer a percentage of a targeted plan’s premium, such as 75% of a gold plan. Learn more about contribution strategies.

Yes. ICHRA can either be used to fully replace your traditional group health plan or you can offer it alongside a group plan for specific employee classes. For example, you might offer a group plan to full-time employees and an ICHRA to part-time employees.

Employee classes let employers offer different allowance amounts and eligibility rules to defined groups, such as full-time, part-time, salaried, hourly, different locations, etc. There are 11 different classes and they are set by IRS regulations. Employees in the same class must be treated equally. Learn more about ICHRA employee classes.

Yes. An ICHRA can satisfy the ACA employer mandate as long as premiums are considered “affordable” for your employees. Learn more about affordability.

Yes. You don’t have to wait for Jan 1st to start an ICHRA. Offering an ICHRA opens up a special enrollment period for your employees. Read our blog article on this for more.

Unused funds stay with the employer. If employees choose a plan that’s less expensive than your contribution, the extra funds stay with the company. You can also choose to reimburse out-of-pocket medical expenses with leftover funds.

ICHRA is available nationwide, but the experience varies with the strength of each state’s individual market. A handful of states have also begun adding their own ICHRA incentives. See what states are doing.

The allowance ends per your plan’s terms — but the employee’s health plan is theirs, not yours, so their coverage continues if they keep paying for it.

An ICHRA and a Premium Tax Credit (PTC) generally can’t be used together. If an ICHRA is considered affordable, an employee isn’t eligible for a Marketplace Premium Tax Credit. If the ICHRA is unaffordable, the employee can choose between accepting the ICHRA or opting out and using the Premium Tax Credit instead. Read our blog article on this for more.

Setting up an ICHRA can happen quickly when we have the information we need to get started. The bigger consideration is timing. Employers need to meet required notice periods and give employees enough time to understand their new benefit, review their coverage options, and choose an individual health plan.

Starting early gives everyone more time to prepare and helps make the transition to an ICHRA as smooth as possible.

Absolutely. Many employers keep their broker for overall benefits strategy while the ICHRA itself is administered by a TPA. We work alongside brokers regularly rather than replacing them.

On the Blog

Latest ICHRA Articles

Get in Touch

Ready to Offer Better Benefits?

We’ll build a side-by-side comparison against your current plan using your actual census, so you can see the real numbers before you decide anything.